Chips

Who buys Nvidia

Everyone calls the AI trade a Big Tech story. Half of Nvidia's new revenue this year came from people you can't name.

Numbers as of 3 Sept 2026

The full story

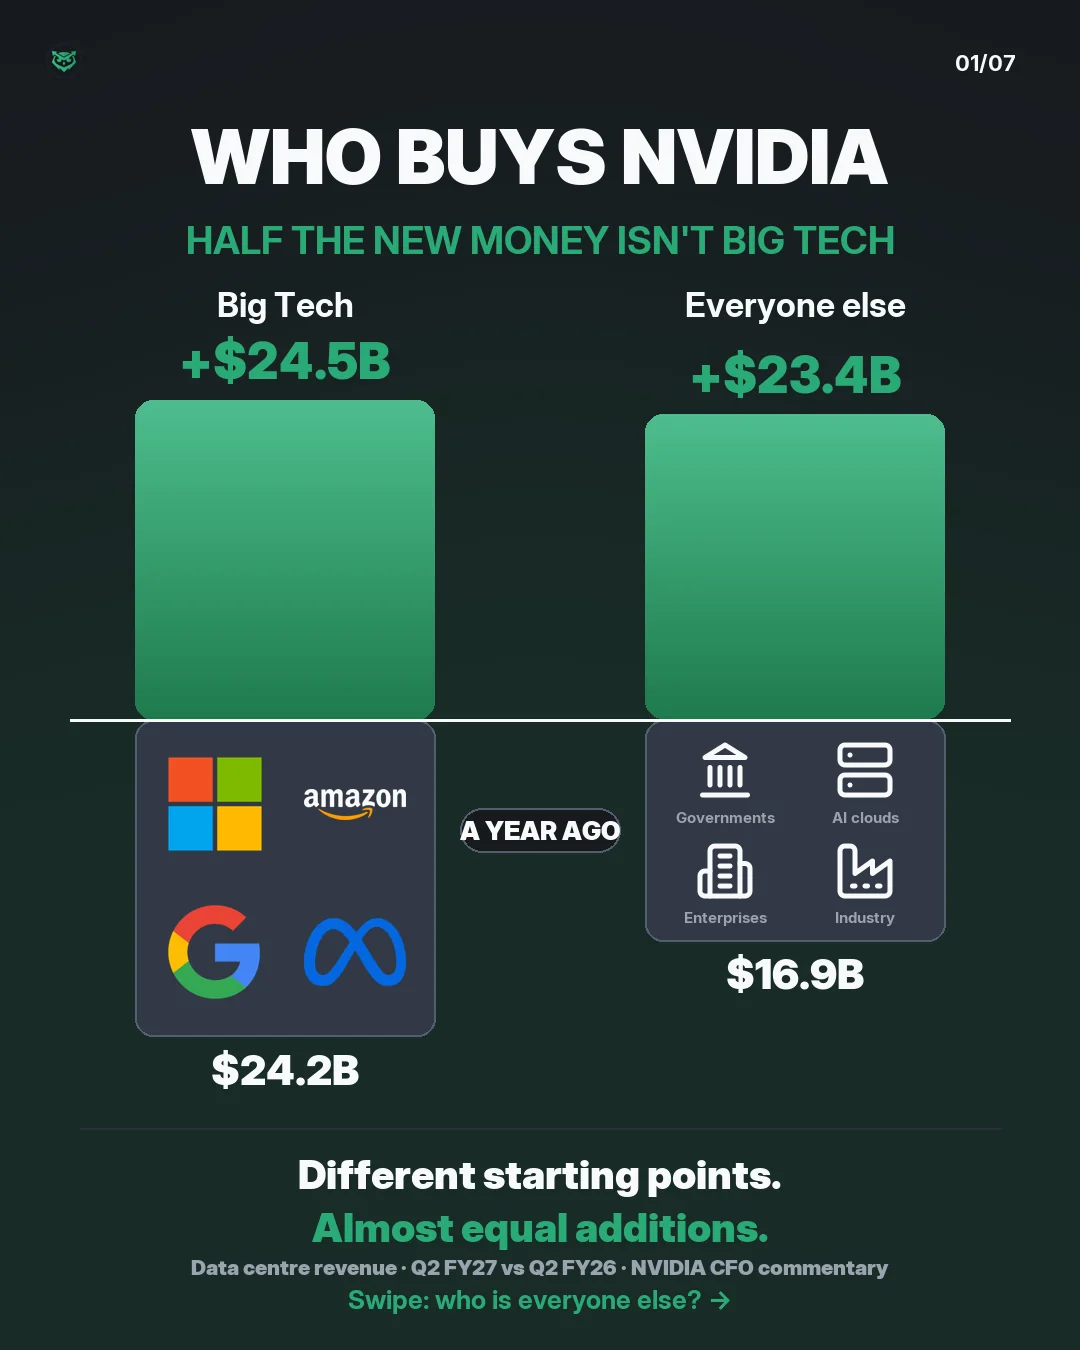
  1. Who buys Nvidia. Two columns either side of a line marked a year ago. Below the line in grey, what each already had: Big Tech $24.2B, everyone else $16.9B. Above it in green, what each added in a year: Big Tech $24.5B, everyone else $23.4B. The two green blocks are almost exactly the same height.
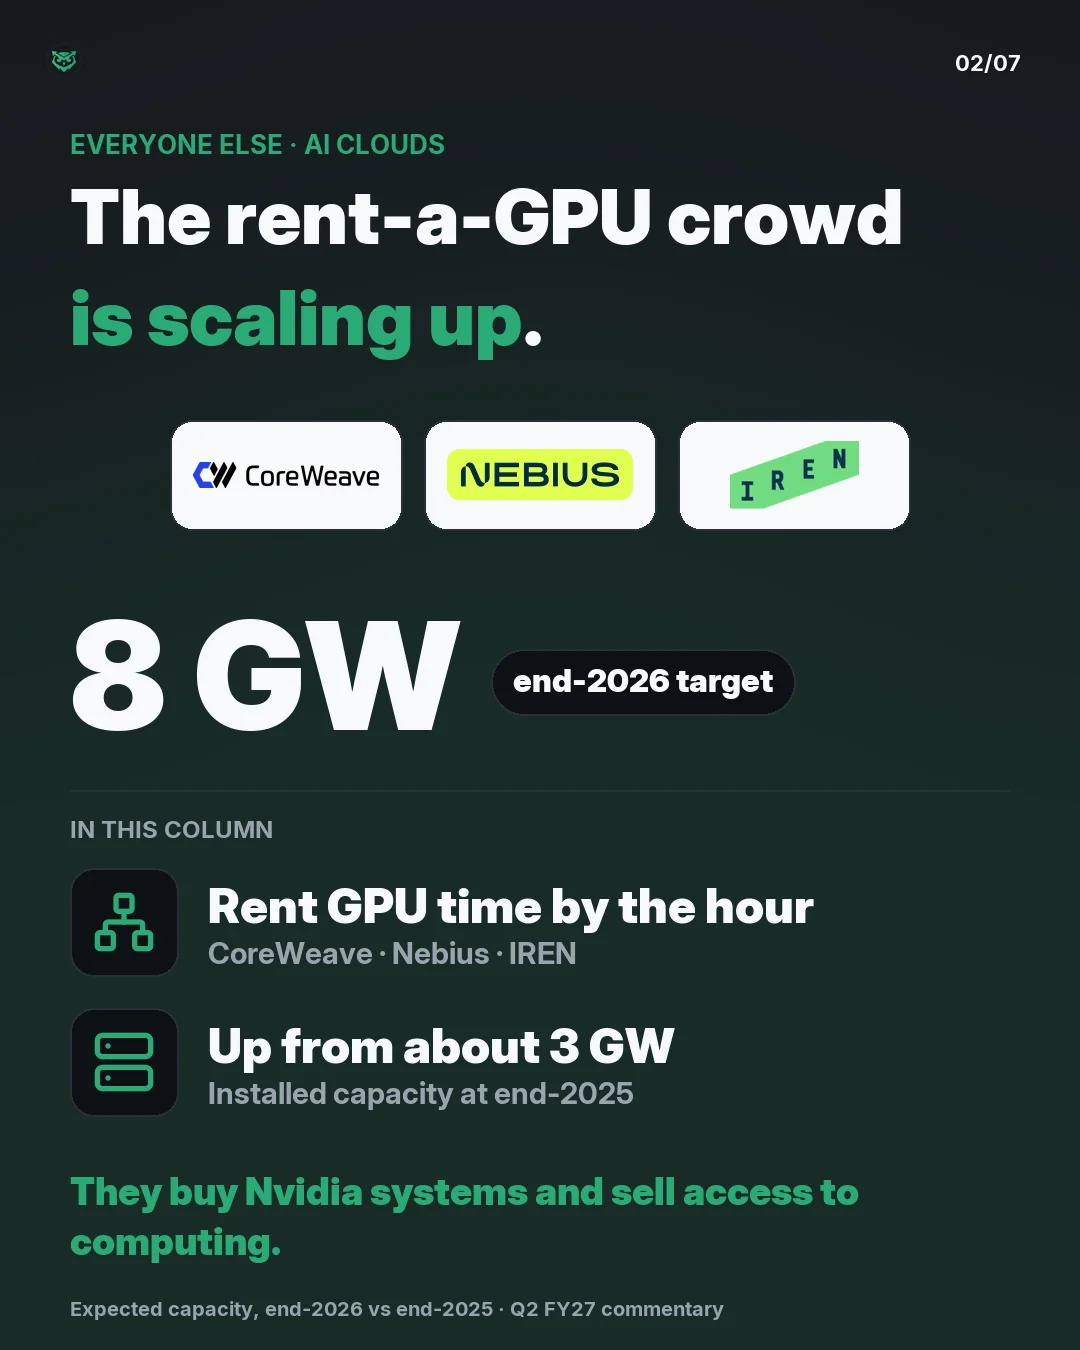
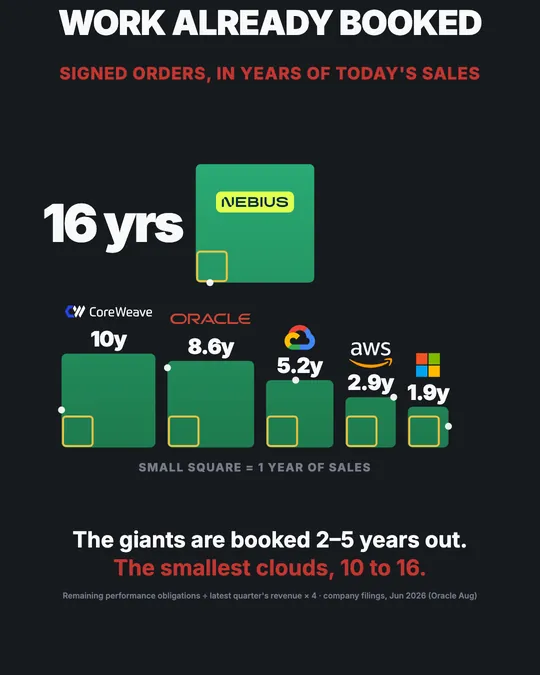
  2. AI clouds. The rent-a-GPU crowd is scaling up. Nvidia expects neocloud partners to reach 8 GW of installed capacity by end-2026, up from about 3 GW at end-2025. CoreWeave, Nebius and IREN are examples of AI clouds. They buy systems and sell access to computing.
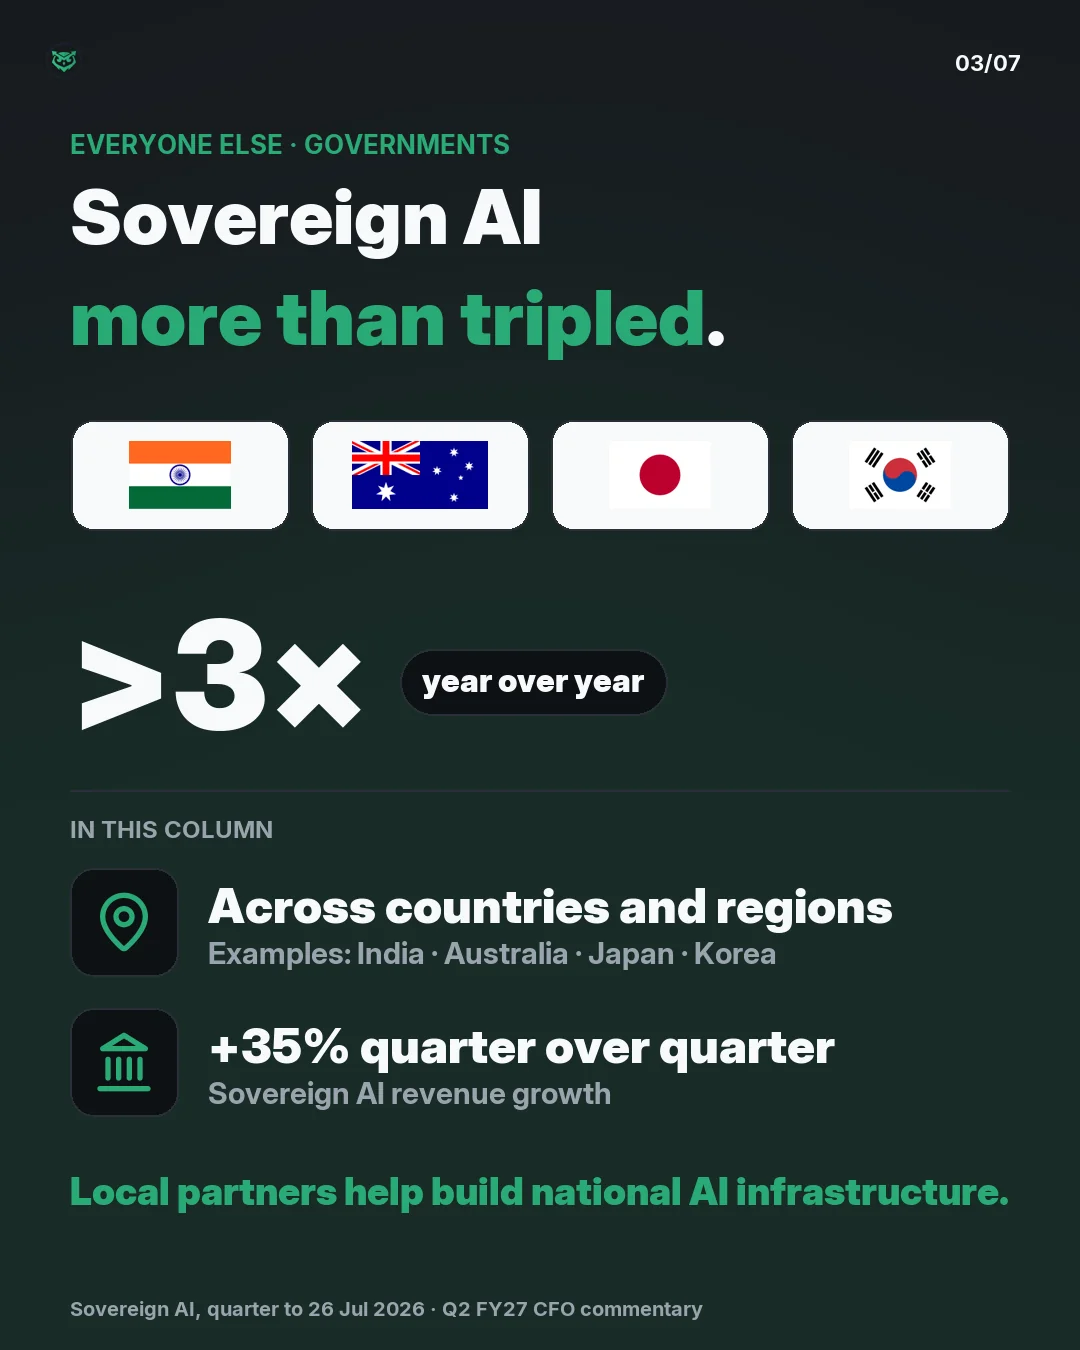
  3. Sovereign AI revenue more than tripled year over year and grew 35% quarter over quarter. Nvidia names partners across countries and regions, including India, Australia, Japan and Korea. Local partners help build national AI infrastructure.
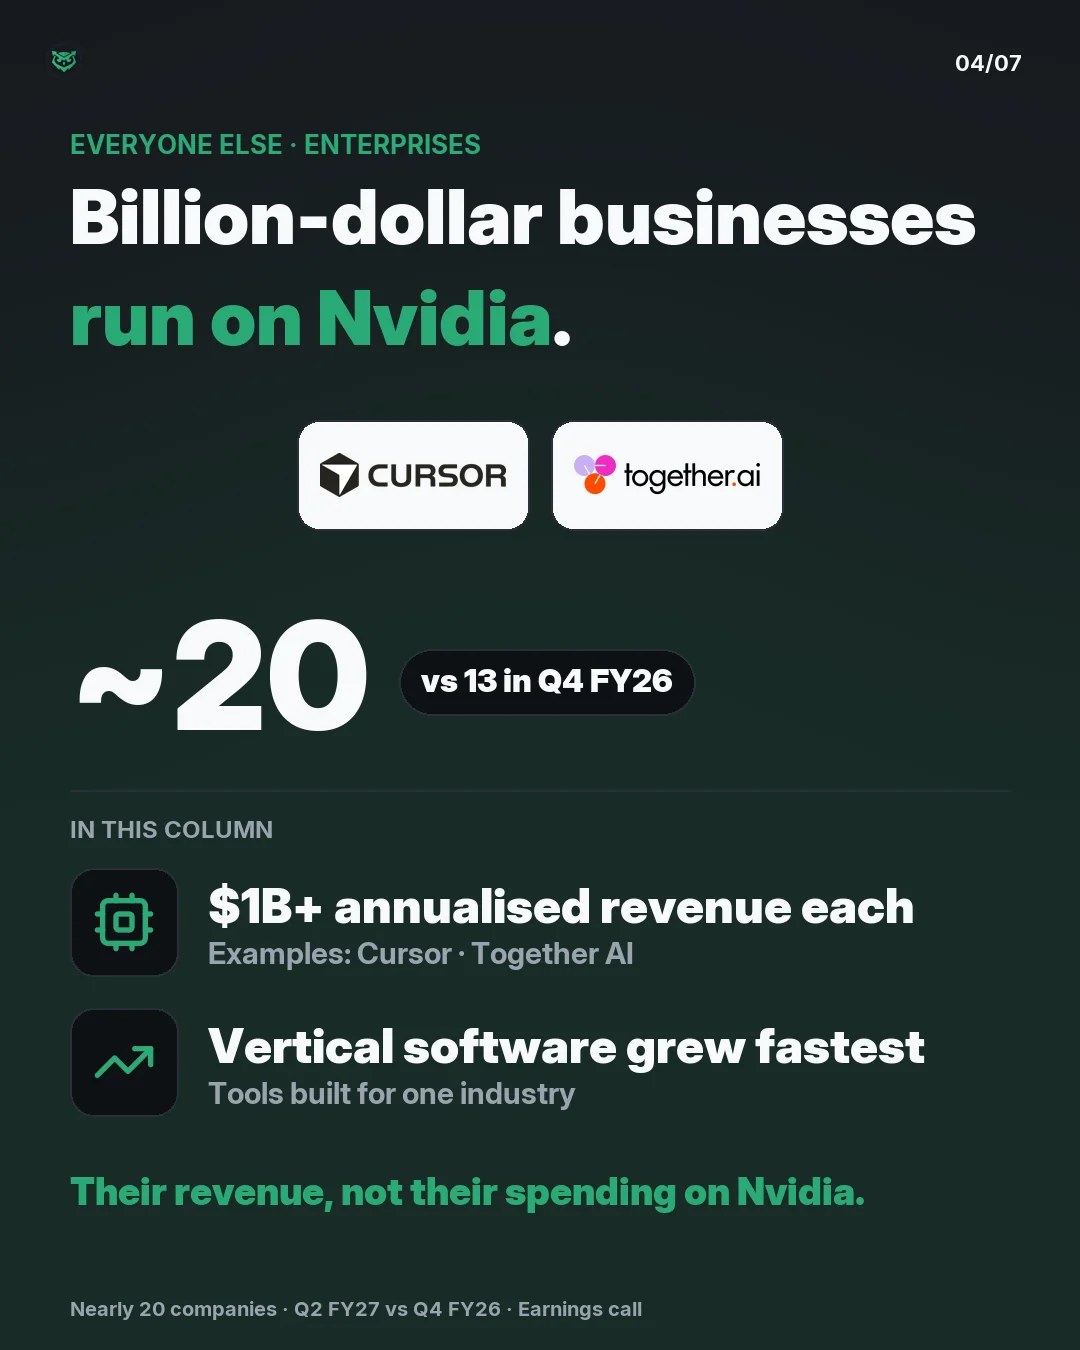
  4. Enterprises. Nearly 20 companies using Nvidia exceed $1 billion in annualised run-rate revenue, compared with 13 in Q4 FY26. Examples include Cursor and Together AI. This measures the companies’ own revenue, not spending on Nvidia. Vertical enterprise software logged the fastest growth.
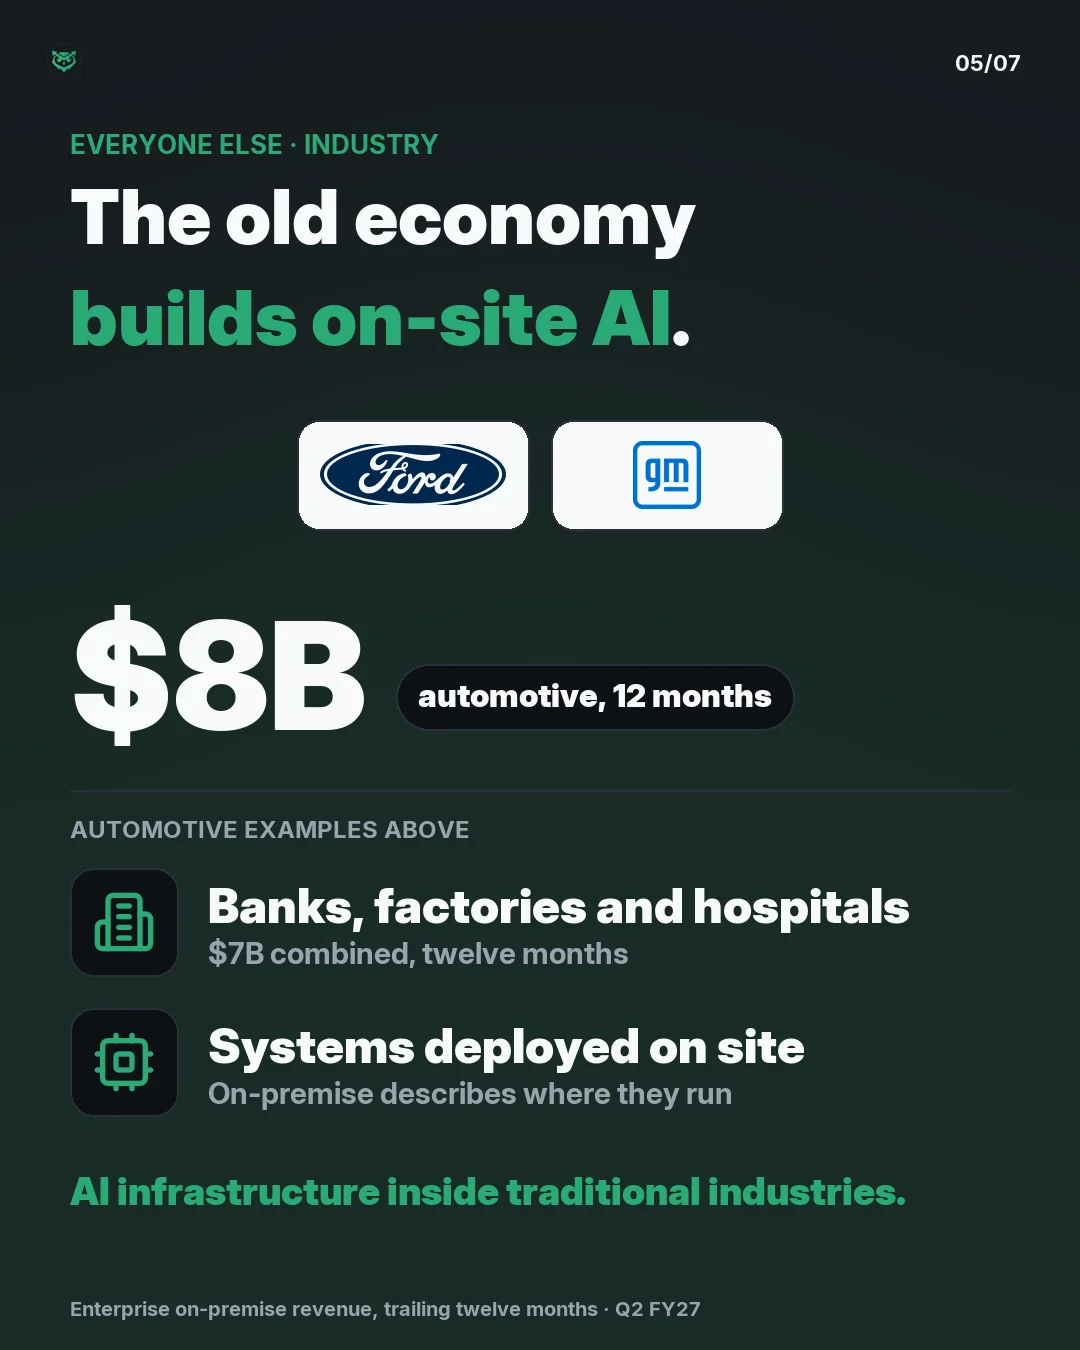
  5. Industry. Nvidia reports $8 billion in automotive on-premise revenue over the trailing twelve months, plus $7 billion combined across financial services, manufacturing and healthcare. Ford and GM illustrate the automotive sector, not the whole $8 billion. On-premise describes deployment location, no
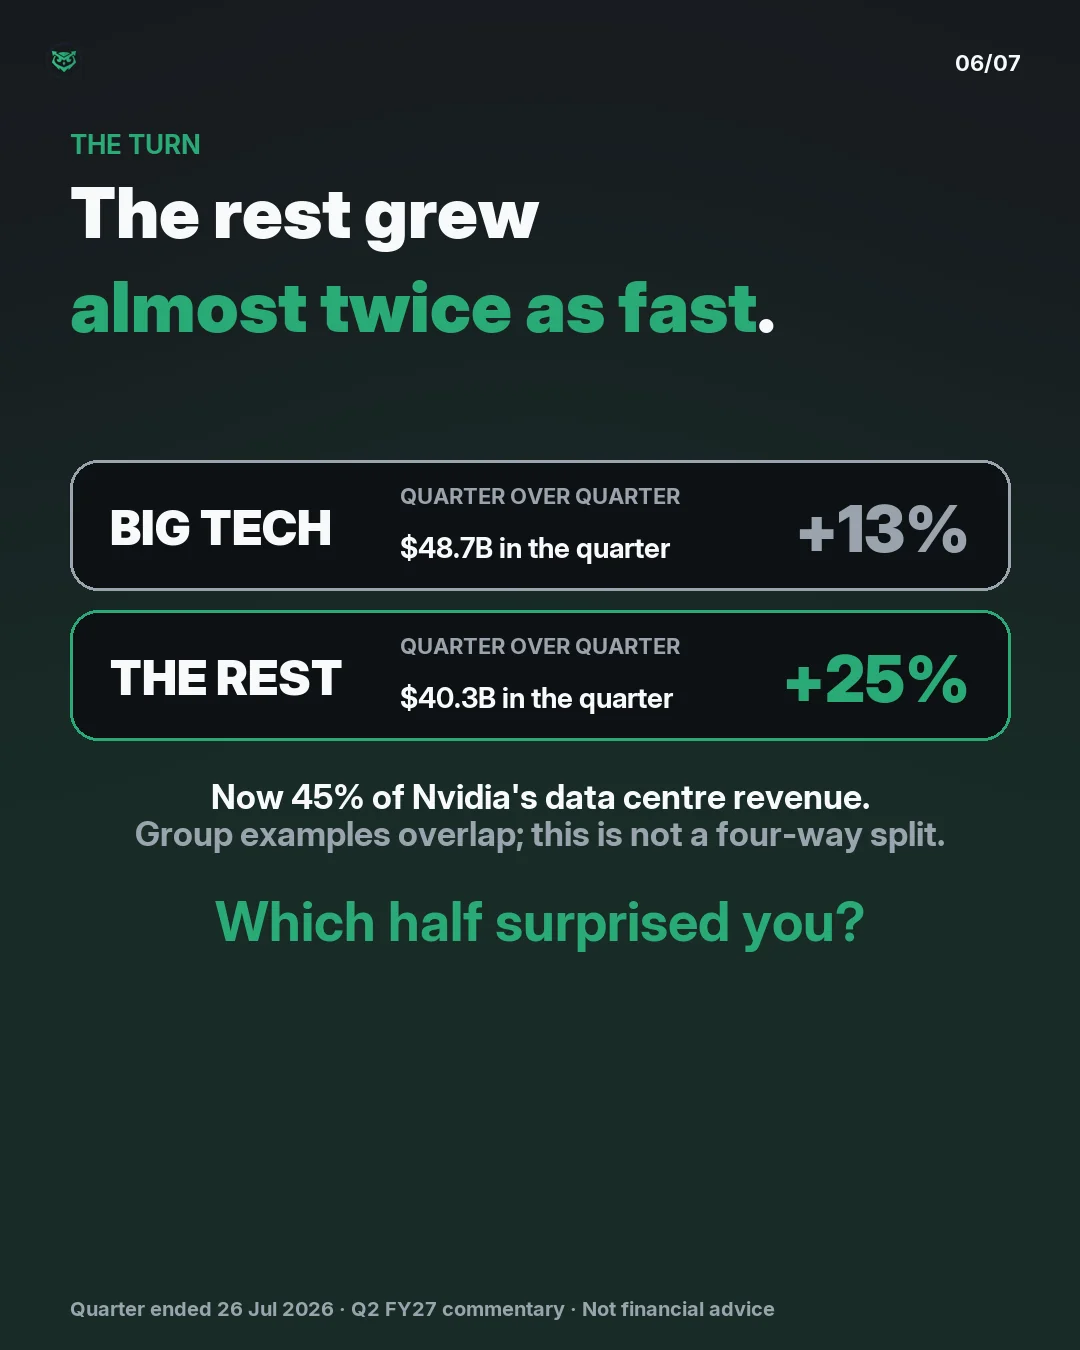
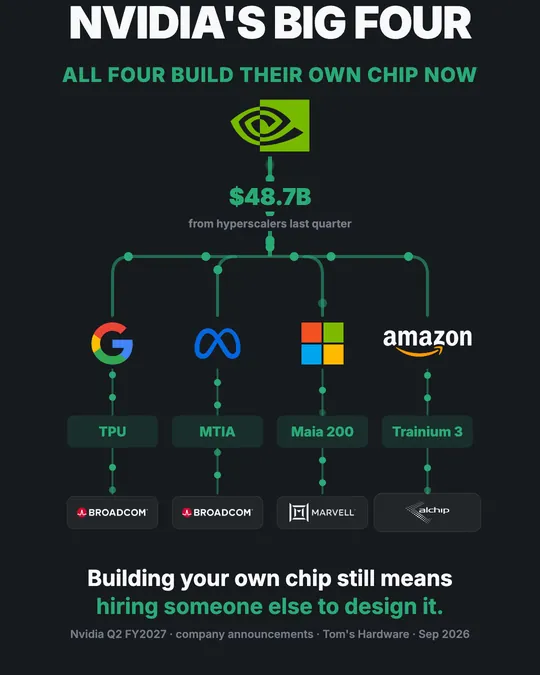
  6. The rest grew almost twice as fast quarter over quarter: hyperscale revenue rose 13% to $48.7 billion, and everyone else rose 25% to $40.3 billion, or about 45% of Nvidia data centre revenue. The four groups are overlapping examples, not an additive revenue breakdown. Which half surprised you?
  7. You may never see our page again if you don't follow. Green Owl, where the money goes, weekly.

Nvidia's data centre business, most recent quarter against the same quarter a year ago:

Hyperscalers - Microsoft, Amazon, Google, Meta and the rest - went from $24.2B to $48.7B. They added $24.5B.

Everyone else - AI clouds, sovereign governments, enterprises, industry - went from $16.9B to $40.3B. They added $23.4B.

Almost exactly the same amount of new money. But they did not start in the same place: Big Tech was 43% bigger a year ago, and is now only 21% bigger.

What is in that right-hand column: sovereign AI more than tripled year over year, and neocloud partners are on track to exit the year at 8 gigawatts of installed capacity against roughly 3GW at the end of 2025.

One caveat on the numbers. The current split of $48.7B and $40.3B is Nvidia's own disclosure and sums to the $89.0B data centre revenue it reported. The year-ago split is derived: data centre was $41.1B and hyperscale was $24.2B, so everyone else was $16.9B.

Management says the non-hyperscale half is heading to roughly half of data centre revenue from here.

Want to see how this looks now?

When enough people ask, we re-check the numbers and redraw it.

Where the numbers come from

Companies in this picture

More like this